
Grey clouds gathered this week; rate rises dampened demand and the prospect of further tax rises in the forthcoming budget had many running for shelter. The forecast of brighter spells, with less property taxation, under a Conservative government… when they can afford it, unsurprisingly did next to nothing to alleviate the nation’s mood. So the market trudged on; each step proving heavier, as house prices continued to fall as construction costs rose. Welcome to another UK Property News Recap – 09.10.2026.
Rate rises dampen buyer demand
As it stands, the autumn/winter collection for lenders looks set to be a poor show. Only those forced to remortgage will be adorning these new 6%+ rates and not willingly.
The full impact on transaction numbers won’t fully be realised till early next year. Those who fixed early will be keen to press ahead and utilise their preferential rate if they find the right property (especially if accompanied with a discount. ) Others will retreat, along with some sellers, over the winter, hoping the New Year will bring peace in the East and with it a reversal in the direction of interest rate travel.
If the global economy should be so lucky… expect a sloth-like descent with one eye firmly fixed on any unexpected movement that could see it race back up again leaving borrowers in a spin once more
Labour weighs up the cost of the mounting debt pile
Given the UK property market is on fire at present…(cough, cough) Instead of putting the flames out, the government is keen to fan them by looking at more ways to squeeze every last bit of tax it can from it. Some of the possible scenarios under consideration are:
1, Reducing the mansion tax threshold to £1.5m from £2m – cue more bunching so as not to hit the threshold and further house price falls. (I suspect this will come further down the line, once they’ve onboarded, and resolved all the contested valuations first.)
2, Increase Capital Gains – expect many to sit on their keys till this, if implemented, is reversed (a definite possibility).
3, All holiday lets pay council tax instead of business rates – easy to do, not going to be well received by the many who have turned to Airbnb so they can sell when the market is better without the fear of a 12-month wait with a typical default assured periodic tenancy, if unsuccessful.
Help to buy up North
Let’s face it…”Your first home” was never meant to help wannabe buyers in the capital without enough capital to reach. Andy Burnham wants to boost growth in the North, where prices are rising and placate builders by putting first timers potentially at risk so they can still build on cheaper land. If prices come down in London, via increased taxation, this is perceived as a good thing for those trying to get onto the London ladder, no matter the rung, but completely disregards all those already on it, especially with hefty mortgages.
More affordable homes will instead be built in London which wouldn’t be a bad thing if they were predominantly council homes but the proportion allotted has already slipped making way for shared homeownership homes, which may appear affordable but are anything but.
“As soon as we can afford it”…
Kemi Badenoch’s open ended promise of scrapping inheritance tax on homes, stamp duty and the mansion tax would have the property market at a standstill, in eager anticipation, should anyone believe the Conservatives stood a chance of getting reelected. BUT…the words “as soon as we can afford it” swiftly snuffed out such a fantastical whim.
Bagging a prime bargain
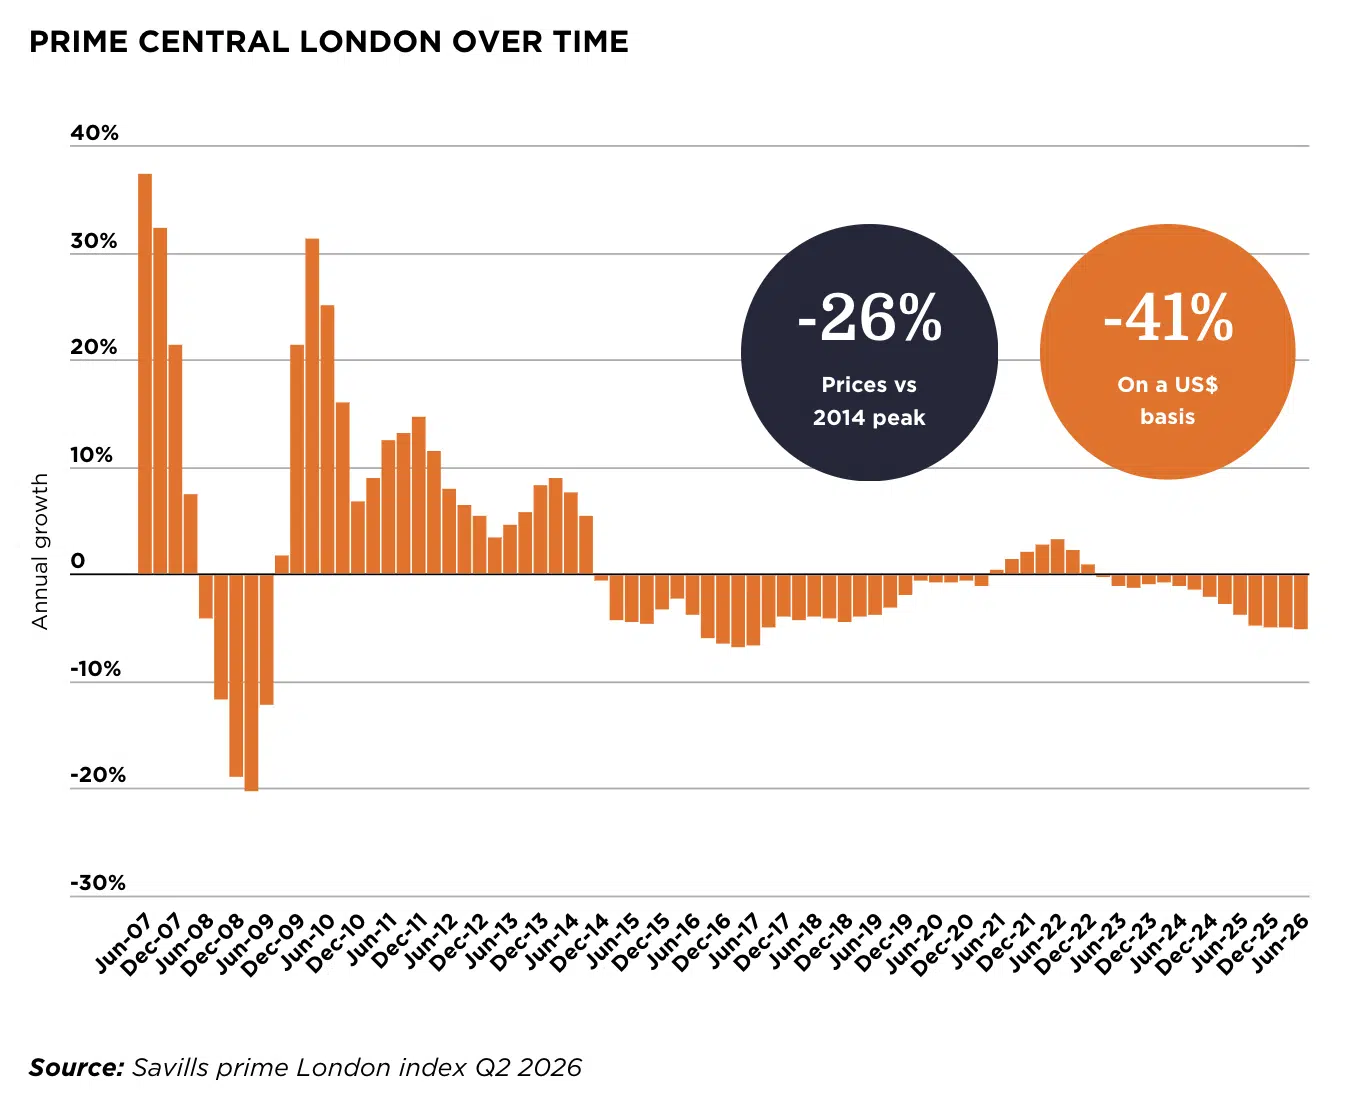
Who stays and who goes – is determined by the size of the property discount. In prime central London, domestic buyers have upped their presence, seeking out addresses once out of reach while North American buyers increased their share of the market – to almost 10% – over the past decade – bagging a piece of historic London at a fraction of the price. Savills found houses continue to be sought after for buyers settled in the UK; be it for schools, work or the AI revolution. These buyers are prepared to swallow the increase in tax to bag a bargain which is generally sizable given values are now -26% below their previous 2014 peak, having fallen by -2.5% so far this year.
Developers ask for more
Not content with the “My First Home” bone thrown. The Berkeley Group, concerned about the “acute crises in London” have written down their budget wish list in the hope the chancellor will come to ‘heal’:
1- Stamp duty on new homes to be scrapped
2 – The 5pc surcharge levied on investors in new-build rental homes to be scrapped
Construction remains banked till the interest rate tide changes
The construction industry remains stuck in a rising interest rate and costs rut, and without some “incentives” it isn’t inclined to climb out.
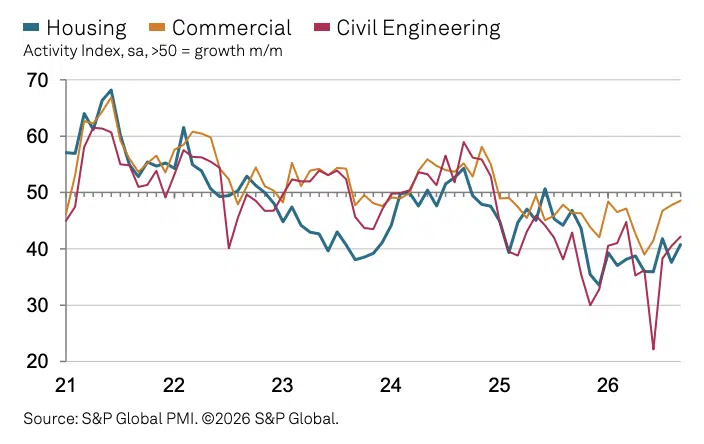
In August the UK construction industry reportedly saw the rate of contraction slow for residential, commercial and civil engineering segments. Housing activity remained the hardest hit while commercial construction demonstrated the greatest resilience, with business activity falling only marginally. New work however plummeted as firms delayed major projects while faced with rising input costs. This led to further job cuts and a sharp reduction in demand for construction products and materials. Leaving any housing target out of anyone’s sight.
Labour halts military housing repair funding
It appears those who serve our country are to be shafted while those who don’t aren’t. Military families are asked to keep a stiff upper lip and live with dilapidated housing for now as £80m of funding is redirected elsewhere.
UK house price growth remains under threat
According to Lloyds Bank’s HPI the average UK house price held steady with 0% growth in August as it continued to ride out the storm coming from the East. The north, showing its affordability mettle, continued to report growth. Northern Ireland was once again out in front with annual house price growth of 7.4%. Scotland and the North West in its slipstream with growth of 3.4% and 2.4% respectively. Meanwhile southern regions remained beached with annual declines of 2.2% in Greater London and 2.1% in the South East – affordability weighing heavy on prices. With rates on the rise and no resolution in sight, the current course looks set to be a bumpy one.
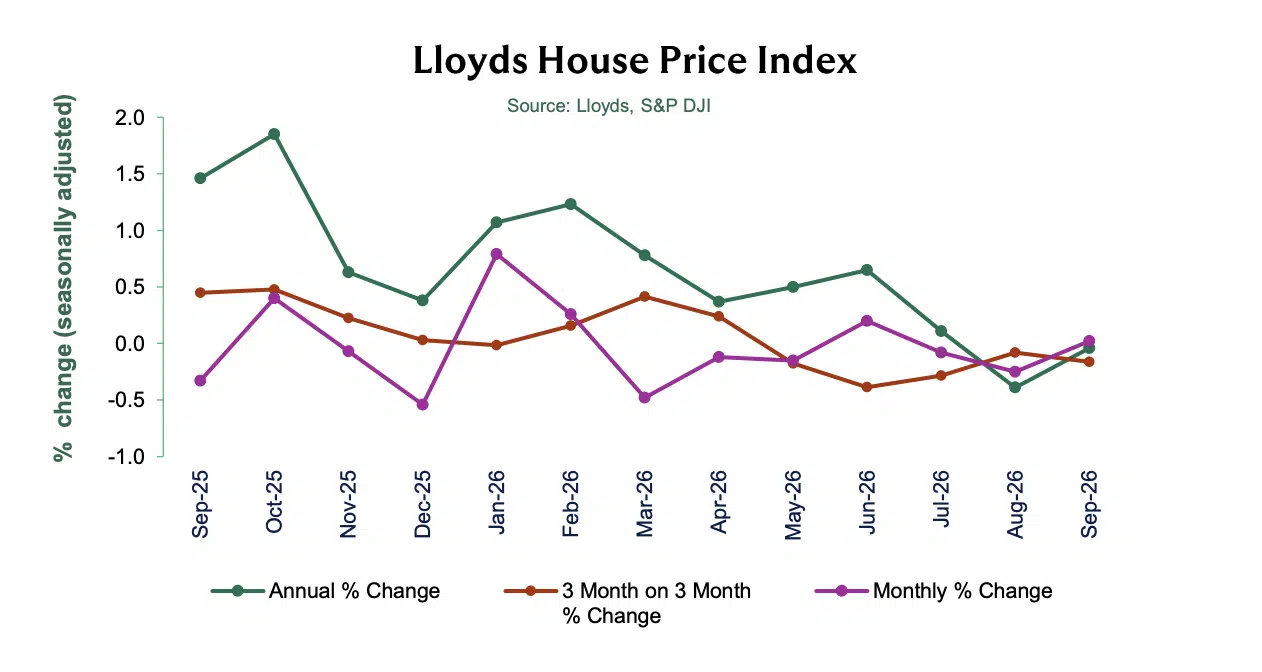
Meanwhile e.surv’s HPI found that in spite of house price growth rising to 1.5% in the year to September, the pace of growth across the UK has slowed. Scotland was still up Y-O-Y but price rises are without doubt decelerating. London remains the hardest hit. Affordability, caution, overtaxation, spiralling service charges and building safety upgrades hitting the market hard….
At the same time e.surv reported almost four in ten London flats sold in 2025/26 after being held for five to ten years sold for less than their previous purchase price. (For houses held for the same length of time, the figure was below 4%.) That is a very hard truth to swallow.
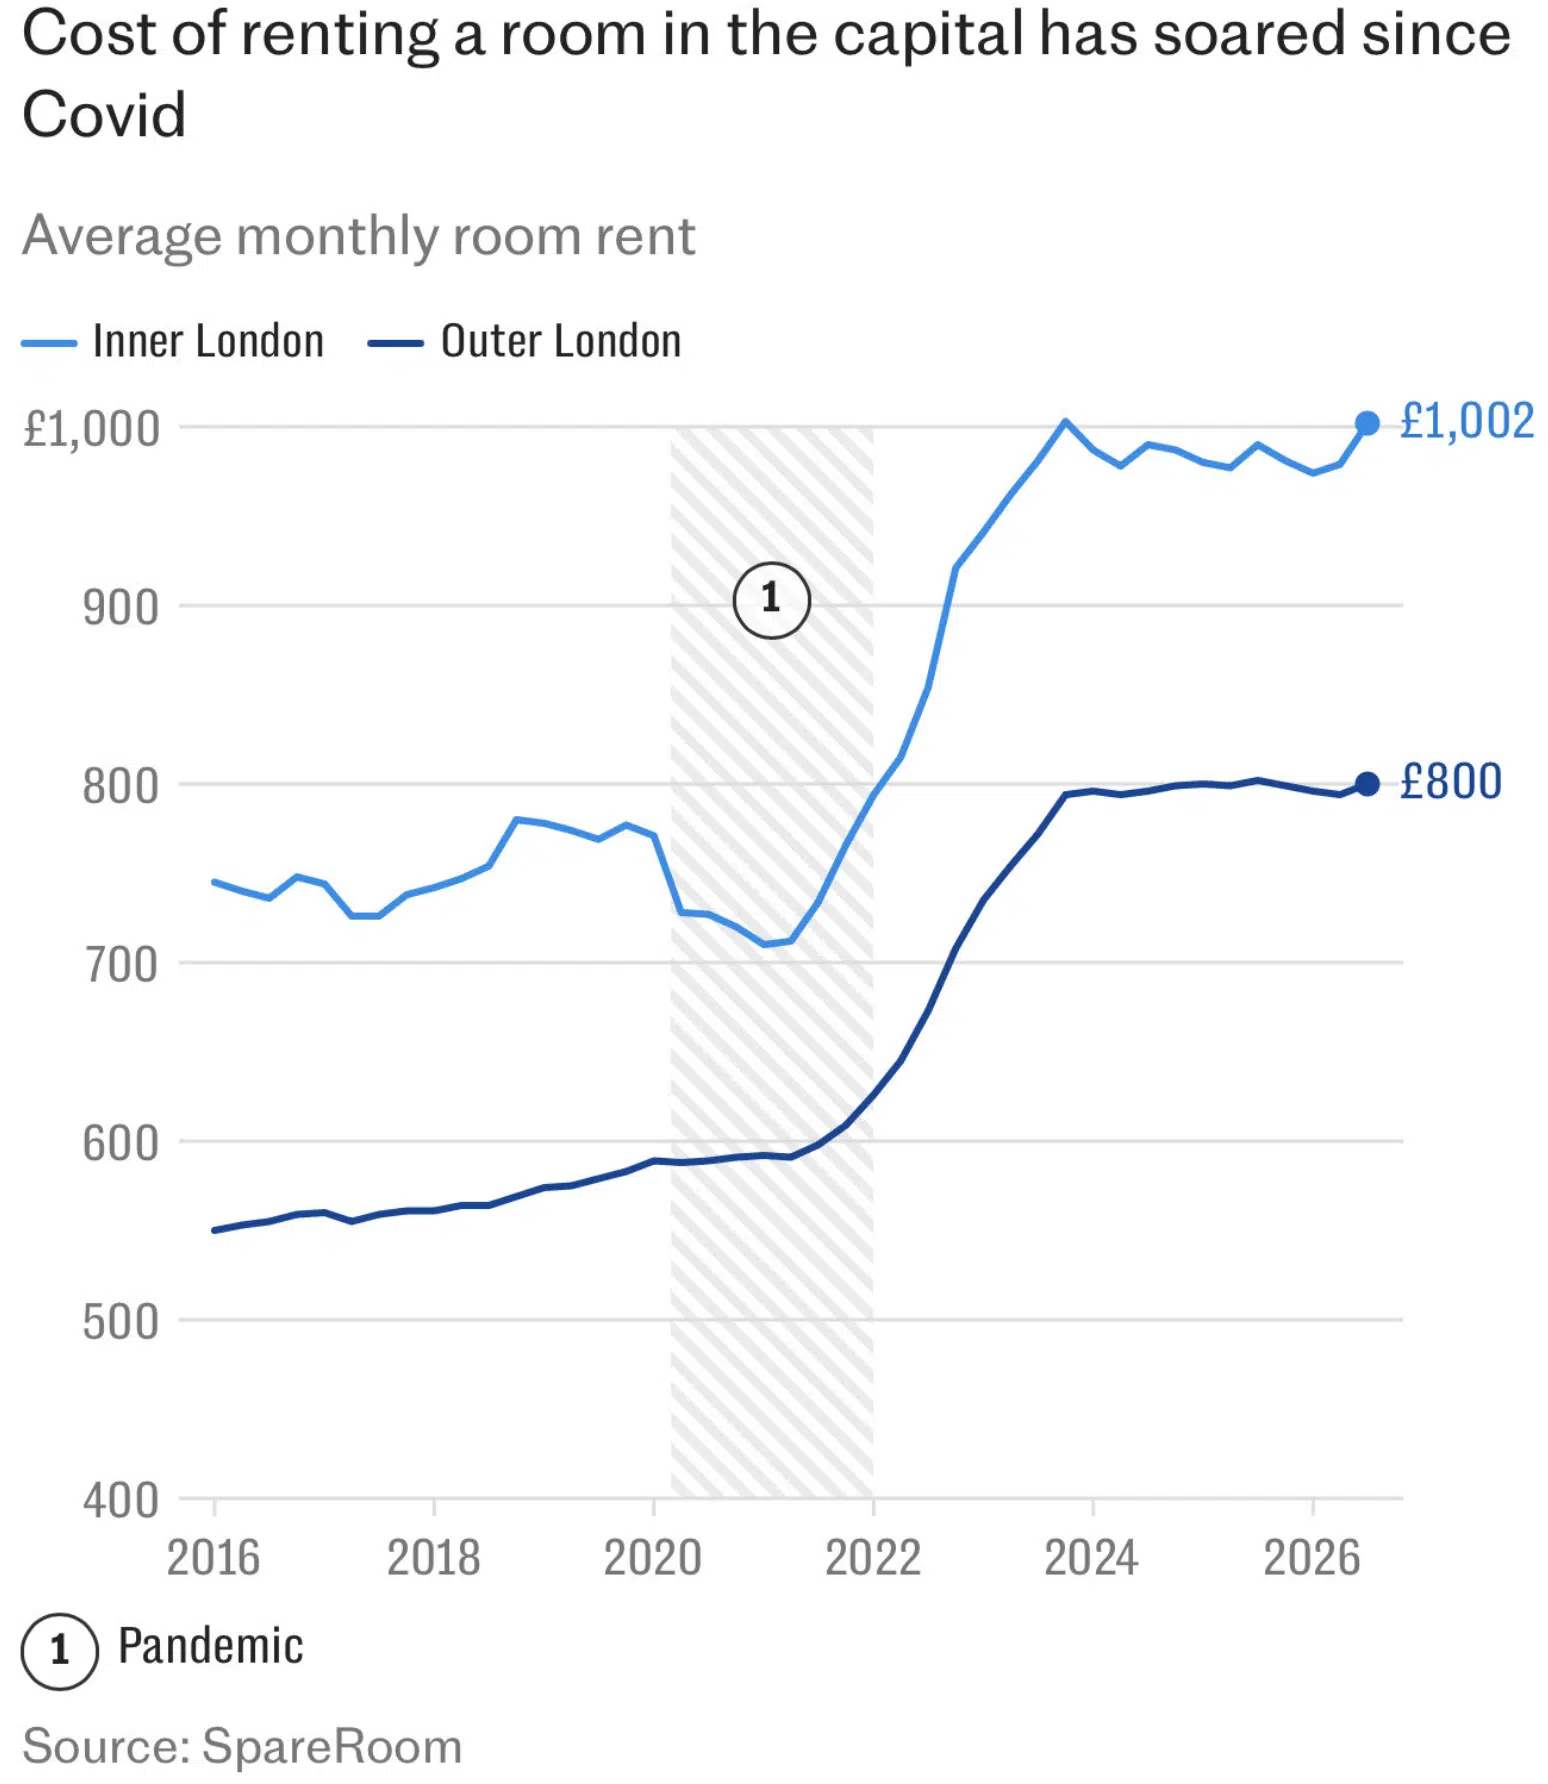
Spare room rates in inner London rise
For some indebted landlords in inner London, it no longer made financial sense. The renters reform bill wasn’t the primary cause, just another nail in an uncertain market. As a result, many sold up, or tried to, while other investors with skin still in the game pivoted northward to more affordable regions to garner larger returns. This loss of historic and cheaper stock caused the price of a spare room to rise to £1,002 a month as tenants battled for more affordable space in central London
Taylor Wimpey exits the London market
Taylor Wimpey is the first of many developers who are hiking Northward, abandoning the Capital, which is no longer commercially viable, for regions where demand can meet more affordable supply.
“The reward for undertaking what is a very high-risk form of development in London has just evaporated,” explained Jennie Daly, CEO of Taylor Wimpey
Local authorities struggling to make planning deadlines
To pass go, developers paid an additional £200m to local authorities over 2022-25 to get a planning framework agreed. The additional “300 planning officers” was never going to cut it. If you want more homes, in a timely fashion, councils need to be ready and well able. The Home Builders Federation found “of the eighty-five responses received from local councils, 12 received more than £1 million through PPA fees over the last three years. The City of London received the highest amount during this period, taking home almost £5 million.” And we wonder why developers won’t build in the Capital…
Autumn prices fall as rising interest rates shake the UK Property Market
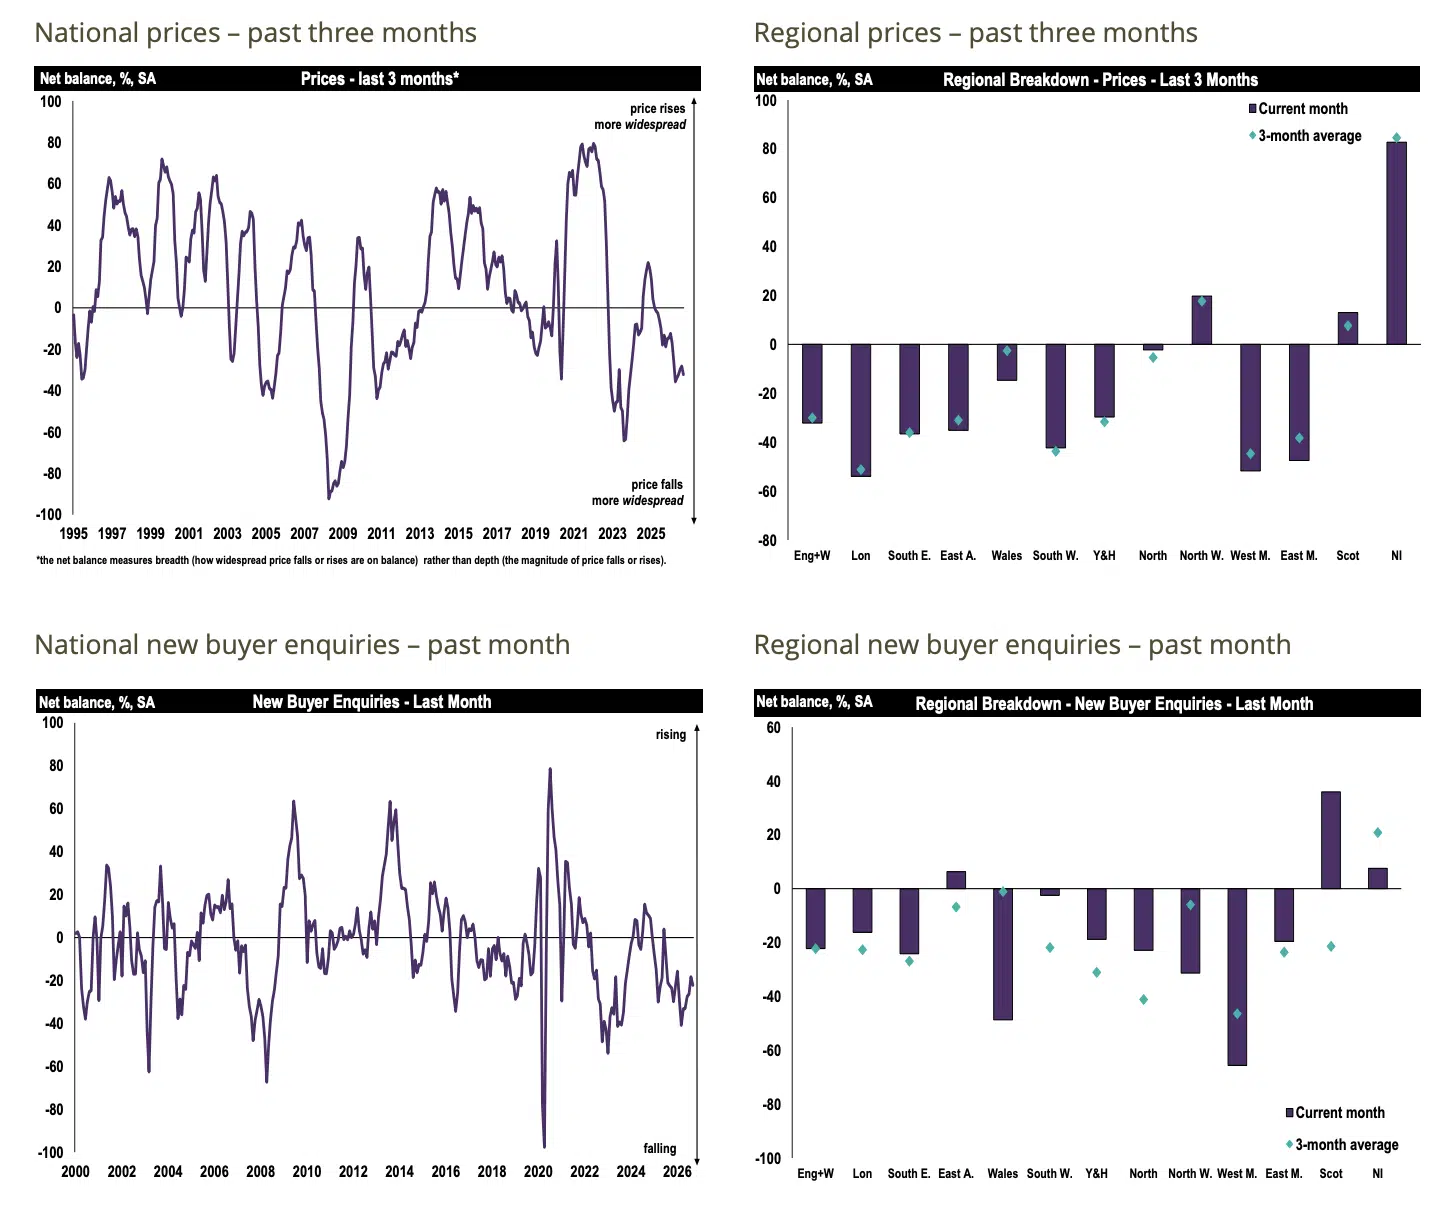
It is no surprise that in this week’s RICS’s Residential Market survey, stock levels were reported to have risen in September. The start of the new term usually heralds an increase in listings from sellers hoping their property will be bagged within the short marketing window that exists before the Christmas party season kicks in. The only difference this year is the bump in listing was contained alongside valuations as market conditions caused New Year deferrals. Many sellers are hopeful that spring will bring new growth.
According to RICS’s surveyors, though, the near future isn’t looking promising. Prices continue to slip across the country especially in London with Northern Ireland and Scotland remaining the main outliers.
Demand remained broadly unchanged since August while agreed sales tentatively improved. Those keen to utilise preferential rates are pressing ahead while others bagged a cash discount.
The UK property market remains on alert – with interest rates on the rise and a budget looming, both buyers and sellers need to tread carefully when moving on.
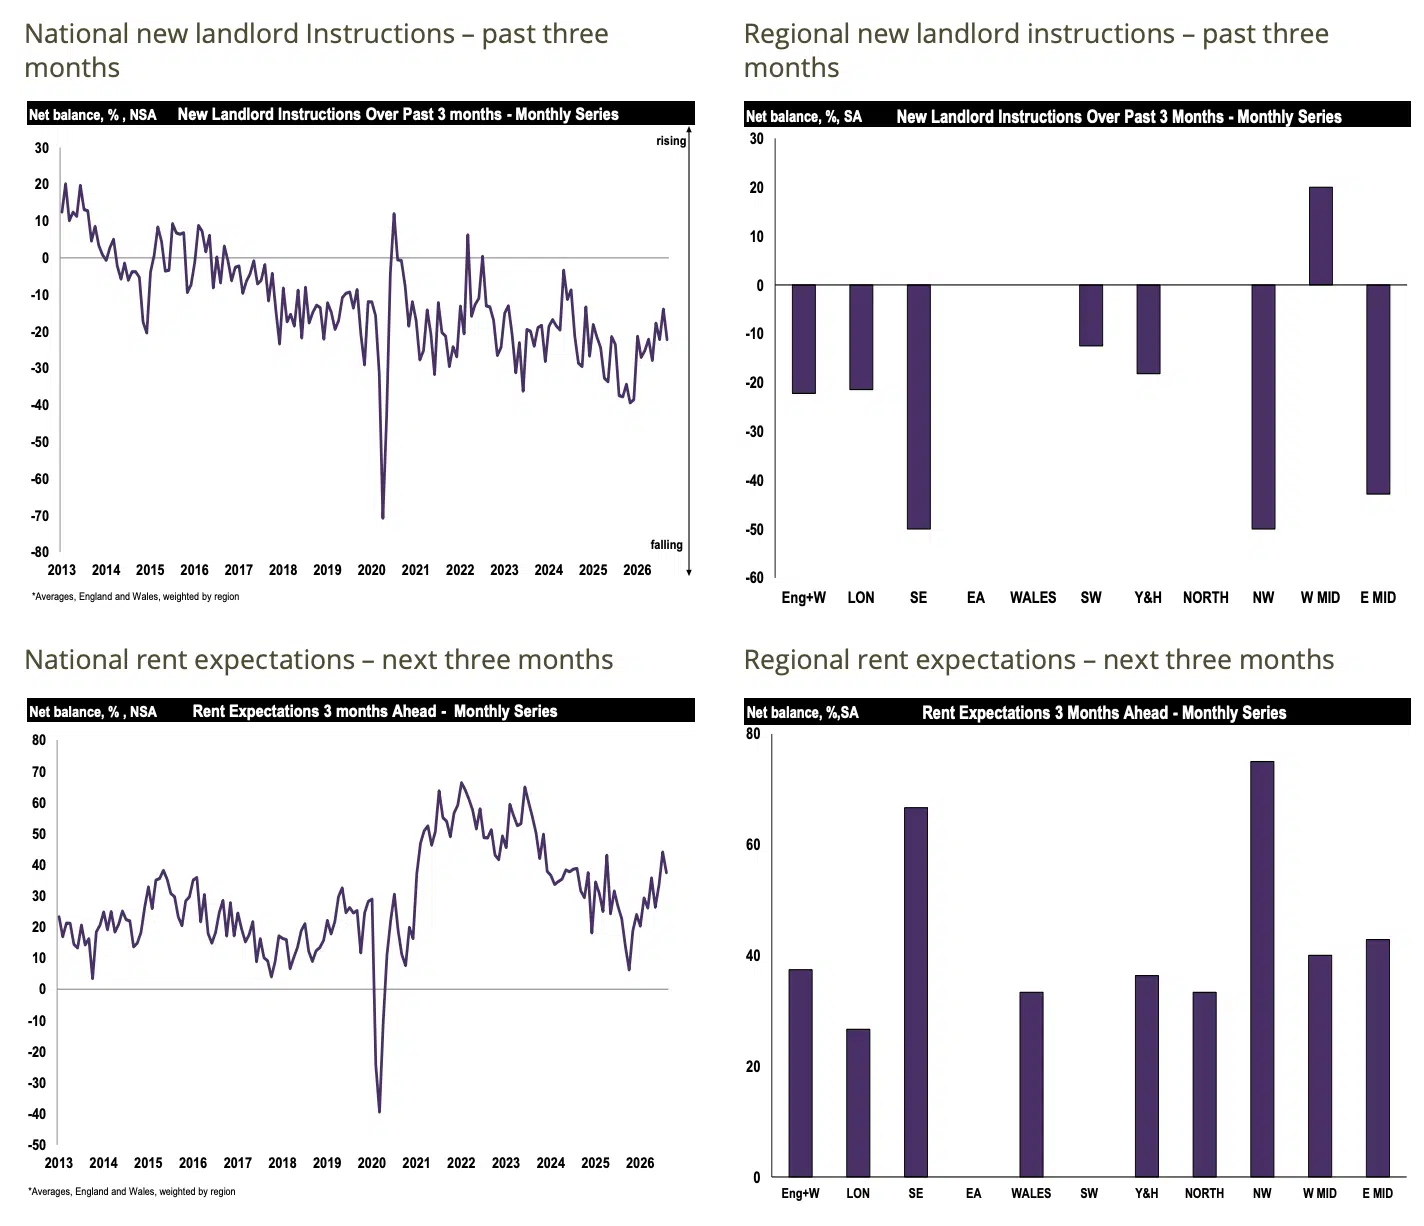
Meanwhile, retreating buyers caused rental demand to rise. Unsupported by supply levels, rents rose with further rises expected, tempered only by affordability.
The FCA anticipates trouble ahead….
Investors in property and infrastructure funds are to be blocked from making daily cash withdrawals. Instead they will have to wait 90 days so as to avoid “liquidity mismatches at funds with hard-to-sell assets” that could lower prices and harm those who remain.
That concludes this week’s UK Property News Recap 09.10.2026. Any comments or suggestions please get in touch.


